Chartered accountant-led bookkeeping on Xero: Ani Advisory keeps the books, so you can run the business.
Monthly bookkeeping, management accounts and SARS compliance for small and medium businesses.
- CA(SA)Chartered accountant
- Tax complianceVAT, IRP6, ITR14
- XeroCloud accounting
- 15+ yearsFinance, tax and audit
What we do
Three services, one set of numbers you can trust
- 01 Accounting services Monthly bookkeeping, monthly management accounts, and annual financial statements prepared under IFRS for SMEs.
- 02 Tax services VAT 201 returns, provisional tax (IRP6) and company income tax returns (ITR14), filed on time inside your Xero records.
- 03 Financial advisory Budgeting and forecasting, and business or project valuations, built on the numbers your accounting and tax work already keeps current.
Who we work with
Built for hands-on business owners
We work best with businesses that keep their books in Xero and want a practice that knows their operations, not just their numbers.
-
Body corporates
Our main focus, and where most of our experience sits.
-
Service businesses
Cleaning, security and garden services, artisans, and small engineering consultancies.
-
Hospitality
Coffee shops and cafes.
- Turnover: up to R100 million
- Structure: not listed, no assets held in a fiduciary capacity
- Location: fully remote, anywhere in South Africa
- System: on Xero, or willing to move to it
What you get every month
The monthly close, done properly
Every month your books are brought up to date, agreed to the statements behind them, and turned into accounts you can actually make decisions from.
-
01
Transactions captured
Income, expenses, assets, liabilities and equity recorded in the right general ledger accounts, in the month they happen, against valid source documents.
-
02
Accounts reconciled
Balance sheet reconciliations between your ledger and the statements behind it, so the numbers are supported rather than assumed.
-
03
Management accounts
A monthly and year-to-date profit or loss, statement of financial position and statement of cash flows, showing where the business stands.
At year-end these roll straight into annual financial statements prepared under IFRS for SMEs, with the accounting policies and supporting notes, ready for SARS, CIPC, lenders and investors.
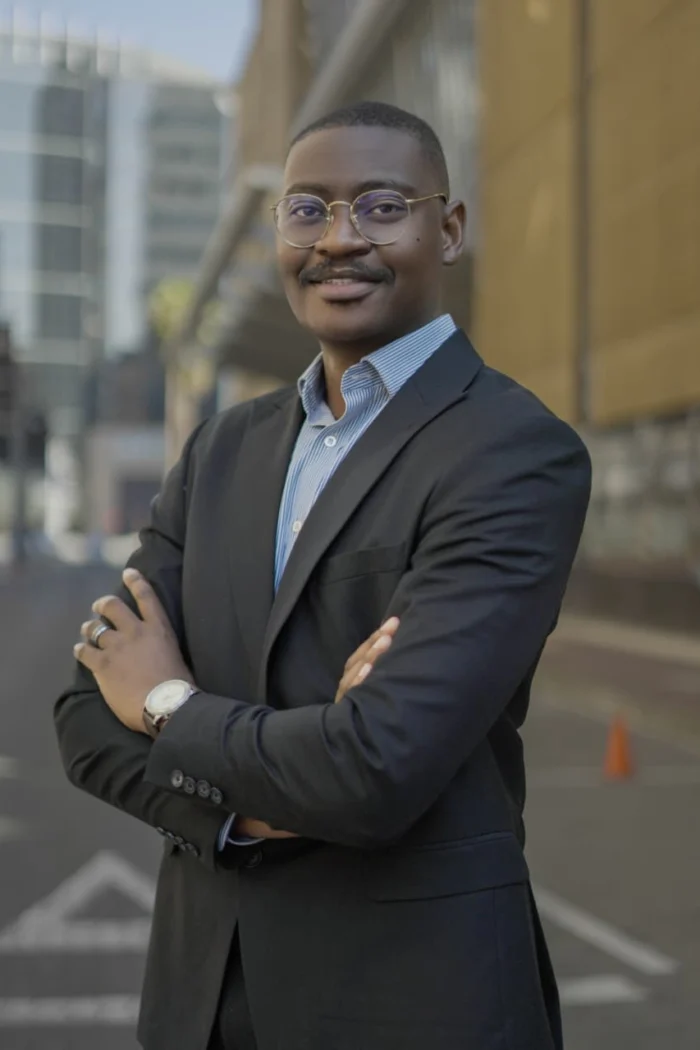
Who you work with
Wisani Mhinga
CA(SA) · Founder
Wisani is a qualified chartered accountant with over 15 years in financial reporting and financial business partnering, across the development finance, banking and audit sectors.
His work has covered variance analysis, group consolidations, external auditing, driving automation, and reporting under International Financial Reporting Standards. That is the experience behind every set of accounts Ani Advisory produces, and behind the advice that comes with them.
Career
- Financial manager
- Financial business partner
- Assistant corporate tax manager
- Auditor
Month-end readiness check
How ready are your books, right now?
Eight questions about how your month-end runs today. You get a score, the gaps behind it, and which service closes each one. No tax advice, no figures, nothing to sign up for.
Takes about two minutes.
Questions we get asked
Straight answers, before you call
The questions South African business owners actually search for, answered plainly. General guidance, not advice for your specific business.
Ask us something elseHow much does a bookkeeper or accountant cost per month in South Africa?
Monthly fees run from a few thousand rand for a small, clean set of books to well over ten thousand once there are high transaction volumes, VAT and payroll. Employing an accountant in-house costs considerably more, once salary, levies and overheads are counted.
Four things move the number: how many transactions you process each month, whether you are registered for VAT, whether payroll is included, and how far behind your books are on day one. A backlog is once-off work and should be quoted separately from the monthly fee. Ask any firm what is included and what is billed extra before you compare quotes.
Ani Advisory's own bookkeeping fee starts from R5,000 a month, which includes your Xero subscription. Management accounts, annual financial statements, tax and advisory work are quoted separately after a short discovery call, based on the size and complexity of your business.
Do I need an accountant if I already use Xero?
Xero records what happened to your money. It does not decide whether the treatment is correct, and it does not take responsibility for what gets filed.
It will also not tell you when it has been set up wrong. If the chart of accounts, tax rates or opening balances are wrong at the start, every report and every VAT return built on top of them inherits that error, quietly. Xero handles the day-to-day well: bank feeds, invoicing, reconciling against the rules you set. What it cannot do is prepare annual financial statements under IFRS for SMEs, choose the right tax treatment, or answer SARS when a return is queried.
We work inside your Xero rather than replacing it. If you're moving from another system, migration happens by taking on the closing balances after your first month-end close with us; because getting that handover right takes care, it isn't included in the standard monthly fee and is quoted separately based on your business.
When must my business register for VAT?
Registration is compulsory once your taxable supplies exceed R2.3 million in any consecutive twelve-month period. That threshold rose from R1 million on 1 April 2026. You may register voluntarily once taxable supplies pass R120,000, up from R50,000 on the same date. The VAT rate remains 15%.
Two things catch businesses out. The test is turnover, not profit: it is the total value of your taxable sales. And the obligation is triggered when you cross the threshold, or when you reasonably expect to, not when you get round to registering. SARS can backdate a registration, with penalties and interest attached.
If you registered under the old R1 million threshold and now sit below R2.3 million, you may qualify to deregister. That is not automatically the right move: stock and assets on hand at the date of deregistration are treated as a deemed supply, and VAT is payable on them. Work out the cost before deciding.
Figures current for the 2026/27 tax year. Thresholds change at Budget, so confirm at sars.gov.za or ask us before acting on them.
What is the difference between a bookkeeper and an accountant, and who may submit my tax returns?
A bookkeeper records transactions and keeps your ledgers current. An accountant interprets those records, prepares financial statements and advises on what the numbers mean. Plenty of businesses use both, and plenty of accountants do both.
On tax the rule is specific: only a SARS-registered tax practitioner may complete or submit a tax return on your behalf for a fee, and that practitioner must be registered through a recognised controlling body. It is a fair question to ask any firm before they touch your returns.
What are monthly management accounts, and does my business need them?
Management accounts are a monthly report of where your business actually stands: what you earned and spent, what you own and owe, and how cash moved. They are prepared for the month and year-to-date, so you see both the month itself and the trend.
Their value is timing. A set of annual financial statements describes a year that ended months ago, which is too late to act on. Monthly accounts let you price, hire, spend and plan against current numbers, and they are the first thing a bank or an investor asks to see.
With Ani Advisory, your pack is delivered as a PowerPoint report by the 15th of the following month, with a monthly call to talk through it.
How do I switch accountants without disrupting SARS and CIPC?
You can change accountants at any point in the year. Nothing in the SARS or CIPC rules ties you to a provider, and your records belong to you.
In practice a handover means three things: moving your SARS eFiling profile to the new practitioner, obtaining your prior-year records and trial balance from the outgoing accountant, and agreeing the opening balances the new books will start from. Timing matters more than the switch itself; moving just after a VAT submission or a provisional tax deadline leaves the most room to pick things up cleanly.